For a Chinese buyer considering a UK flat, the purchase price and mortgage amount are only part of the decision. Many flats are leasehold, which means the buyer acquires rights under a lease for the remaining term rather than the freehold of the building. The lease length, annual charges, planned works and use restrictions can affect both the household budget and a lender’s view of the property.
GOV.UK explains that the lease term runs from the date the lease was originally created and does not restart when the flat is sold. Its guidance says lenders are typically less likely to provide a mortgage where fewer than 80 years remain. This is general consumer guidance, not a universal lender threshold; the actual provider and conveyancer must confirm the position for the selected property.
Ask for the lease start date and remaining term early, then have the conveyancer check the lease itself. An estate-agent description is not a substitute for the legal document. If an extension may be needed, establish who can apply, the likely process, timing and cost before treating the flat as equivalent to a longer-lease property.
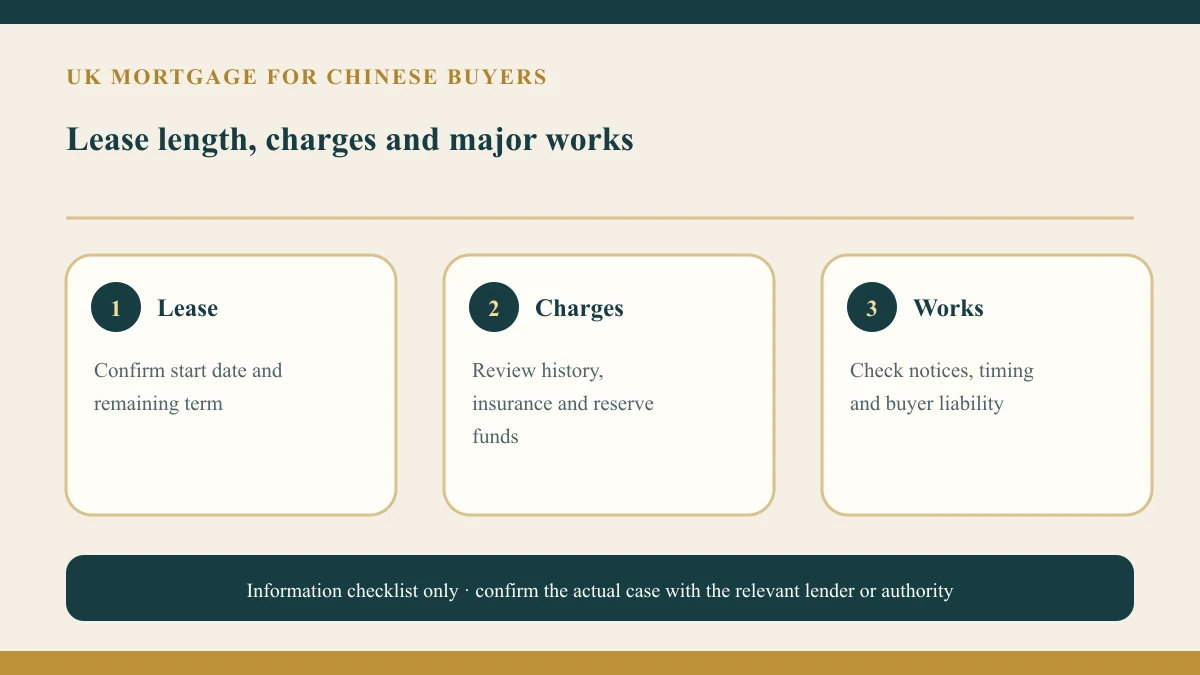
Service charges need their own evidence. GOV.UK recommends checking the current charge, what it covers and, for a resale property, at least the previous two years so that changes can be seen. A mortgage budget should distinguish the mortgage payment from service charge, building insurance contributions, ground rent where applicable, administration fees and any reserve or sinking fund.
Major works can create a separate cash requirement after completion. Ask whether works have recently been completed or are planned, whether formal notices exist, how the buyer’s share is calculated and whether a reserve fund is available. Do not assume that a normal current service charge means there will be no additional demand after the purchase.
The lease may also restrict subletting, alterations, pets or other uses and may require the freeholder’s consent and a fee. This matters if the buyer expects to let the flat or remodel it. The mortgage provider’s permission, the lease terms and local legal requirements are separate checks; approval from one party does not automatically satisfy the others.
Before making an irreversible commitment, organise the lease, management information, service-charge history, major-works correspondence and building-insurance details for the conveyancer and lender. A mortgage valuation does not replace this legal and financial review. The goal is not to predict approval, but to ensure that the loan, property rights and ongoing costs describe the same property plan.
Sources and scope
- GOV.UK buying or owning a leasehold home(2026-09-29复核)
This article organises public information and does not provide personal mortgage, legal or tax advice. Confirm the current position with the relevant lender, conveyancer, HMRC guidance or a qualified adviser.
Related information and consultation
Related pages: UK mortgages、mortgages for non-residents. Use the consultation page to organise questions; acknowledgement of an enquiry is not mortgage approval.