01REVIEW POINT
Show how wealth arose
Salary savings, dividends, asset sales, investment redemptions, inheritance or gifts should connect to contracts, tax, bank and identity records.
Source of funds is not a balance screenshot. It is a continuous record of how money was lawfully created, who owned it, how it moved and how it reaches the UK transaction account. Lenders, solicitors and banks may ask separate questions under their own responsibilities.
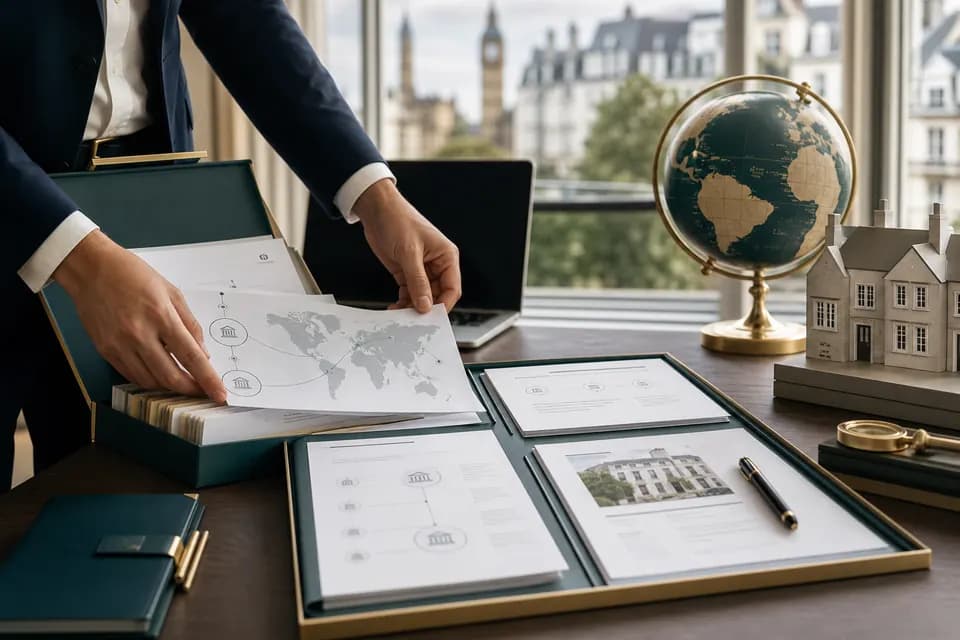
Organise evidence for savings, gifts, asset sales and cross-border transfers and understand why lenders and solicitors may ask different questions.
Salary savings, dividends, asset sales, investment redemptions, inheritance or gifts should connect to contracts, tax, bank and identity records.
Avoid unnecessary temporary layers. Material credits and transfers should have an identifiable source, purpose, date and counterparty.
The donor's identity, relationship, source, repayment position and any property interest may need written confirmation and bank evidence.
Bank queries, transfer controls, translation, certification and time zones can affect completion, so work backwards from the solicitor's deadline.
Exact requirements differ by lender and case. These items make an early review more useful.
It may be. The location of an account does not explain how the money was created or transferred.
Potentially, but the lender and solicitor may check donor identity, source, relationship and rights. Requirements are case-specific.
They have different compliance and professional duties, so their tests and record-keeping requirements may not be identical.
Our content draws on formal lender documents, public regulatory and government material, transaction professionals and verifiable client evidence, with a prompt to check current conditions before key decisions.
General information: This page is general information, not an individual mortgage recommendation or legal, tax or investment advice. Eligibility, LTV, pricing, fees, valuation and approval are decided by the relevant provider for the applicant and property at that time. Read formal documents and obtain appropriate independent advice before signing or transferring funds.
Share your residence, income type and currency, property use, budget and timing so we can identify eligibility and evidence gaps. Identity documents and full bank statements are not needed for the first conversation; an initial review does not guarantee approval.
Book an initial conversation →