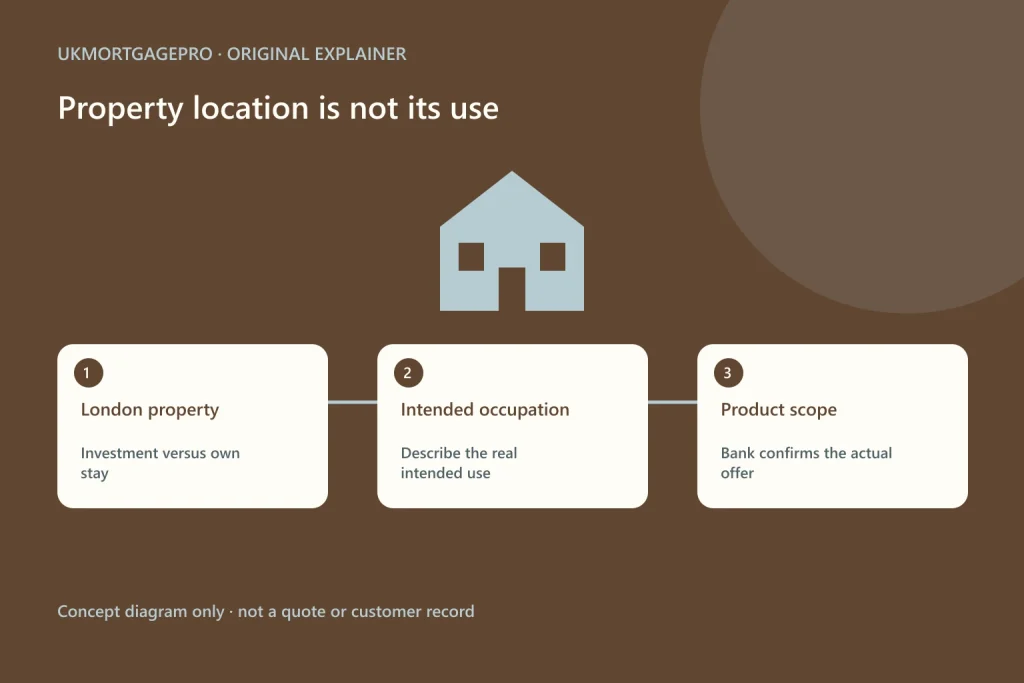
Start with what the property will be used for
A Singapore bank UK mortgage enquiry should explain the intended occupation, not just the city and purchase price. A buyer planning to live in a London home, let it to tenants or make it available to family is describing different circumstances. This article focuses on the investment-use boundary in OCBC’s public overseas-property product, not refinancing documents or currency selection. It does not conclude that a particular buyer or property qualifies, and it does not recommend the product.
Read beyond the general headline
OCBC’s overseas-property page says it can finance purchases or refinance overseas property loans, then narrows scope by location. It states that, other than Malaysian properties, only investment properties qualify for that product; its UK section describes London property financing. Those statements need to be read together. The headline does not prove that every overseas home, every UK location or an owner-occupied London purchase is eligible. Current case conditions must be confirmed with the bank before relying on a financing assumption.
Eligibility has more than one layer
A property may be in the named location but have an intended use outside the product scope. An applicant may meet one public residence description but fail another part of the bank’s assessment. Neither fact should be concealed or inferred from a brochure. Give the responsible professional a consistent account of the borrower, property and intended occupation. This article avoids reproducing live rates, minimum loan sizes or loan-to-value figures, because those would not establish approval and can change.
Own occupation is not ordinary investment letting
Do not describe a planned personal stay as investment letting merely to match an application field. If use is mixed, temporary, by family members or expected to change, explain those facts and ask the bank how they are treated. A website’s general wording does not answer every borderline situation. The legal, insurance and tax implications may also differ and need their own professional review. A broker or information site cannot grant the bank’s permission on the strength of a general product page.
Family use needs an explicit question
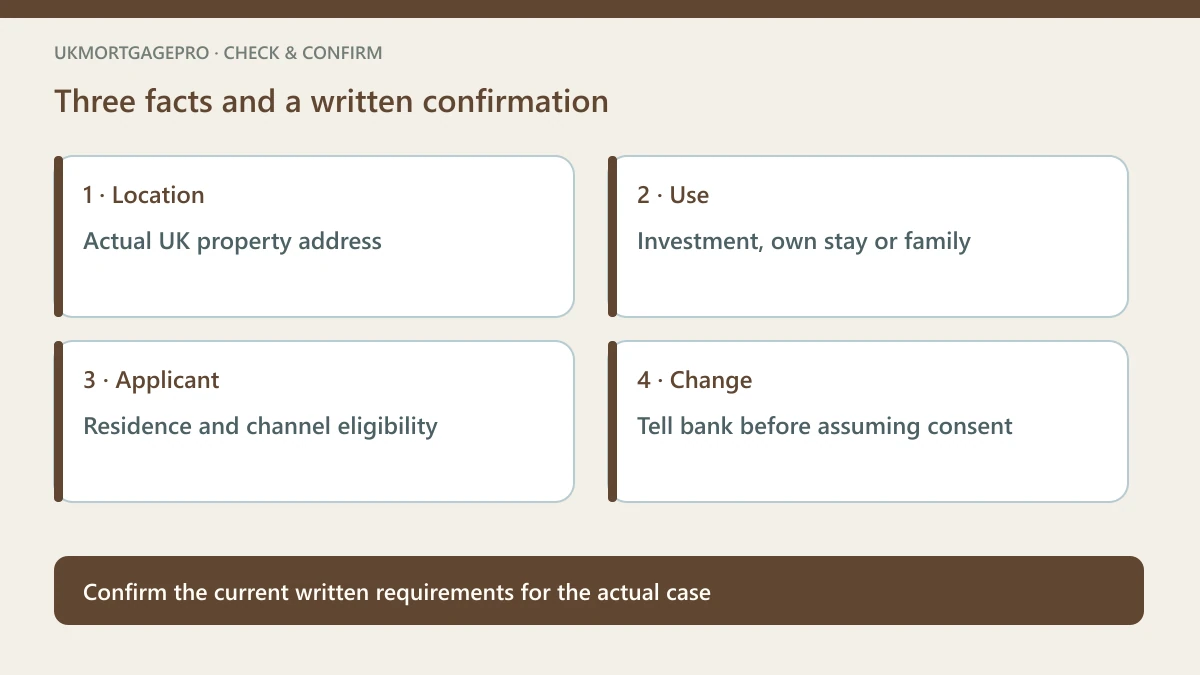
Buying for a child studying in the UK or for relatives is not automatically the same as a property let to unrelated paying tenants. Rather than guessing the category, give a short factual description of who will occupy it, whether rent is intended and whether the borrower will also stay there. Ask for a written answer about this actual use under the proposed product. Do not assume a different bank’s family-occupation policy applies to OCBC or to all Singapore overseas-property facilities.
Separate a use restriction from a mortgage amount
A sufficiently large deposit does not automatically remove an investment-use restriction. Nor does an attractive indicative rate make an otherwise excluded use acceptable. Compare policy fit before detailed product costs, and mark the enquiry as unresolved if the occupation question has not been answered. The actual bank offer and conditions should control the case. The site does not have authority to waive a restriction, accept a different use or say that the bank will overlook it at completion.
If plans change, keep the facts aligned
After a financing enquiry or offer, a change from letting to personal occupation should be raised with the bank and the relevant professionals. Do not assume an earlier approval automatically covers a new purpose. Similarly, an existing lease or prior investment use does not establish permission for a future owner’s plan. The relevant professionals need to confirm the actual product and property conditions before a new use is treated as permitted; this article cannot make that case-specific determination.
Other channels remain separate possibilities
If the described OCBC product does not match the real occupation plan, an adviser may discuss whether another appropriate route exists. That is a new eligibility check, not a guarantee of a substitute mortgage. Do not combine one lender’s use policy with another’s rate or infer a bank partnership from a website reference. A UK residential mortgage and a Singapore overseas investment-property facility can have different product purposes, documents and contractual conditions. The comparison should preserve those distinctions.
Make the first enquiry precise
An initial enquiry can state the proposed London location, applicant residence and genuine occupation plan without uploading private identification or contracts. The useful next step is written clarification of product scope and required evidence. UKMortgagePro provides an information and consultation path, not OCBC approval, representation or investment advice. The first-party page was read on 3 October 2026; scope and terms should be reconfirmed for the formal case. Property financing carries repayment and investment risks even if the intended use is permitted.
Practical checklist
- The UK-location section and investment-use restriction are read together.
- The real occupation plan is stated without relabelling.
- Family or mixed use is raised as a specific question.
- The bank’s actual conditions remain separate from other lenders’ policies.
Questions to clarify
Does a London address make own occupation eligible?
Not by itself. The product’s location and use boundaries both need to fit the actual case.
Can a larger deposit override the stated use restriction?
Do not assume so. Only the bank can confirm its actual product conditions for the application.
Sources and scope
- OCBC Singapore — Overseas Property Loan — checked 2026-10-03; page publication/update date not stated or not established
Public information and document-organisation guidance only; not personal mortgage, legal, tax, valuation or investment advice, and not lender approval or endorsement. Confirm current case requirements with the responsible professionals.
Related information and consultation
Singapore-bank UK-property finance · Non-resident mortgage information · News and practical guides · Arrange a consultation。Enquiry acknowledgement is not mortgage approval.