Ask who does which work
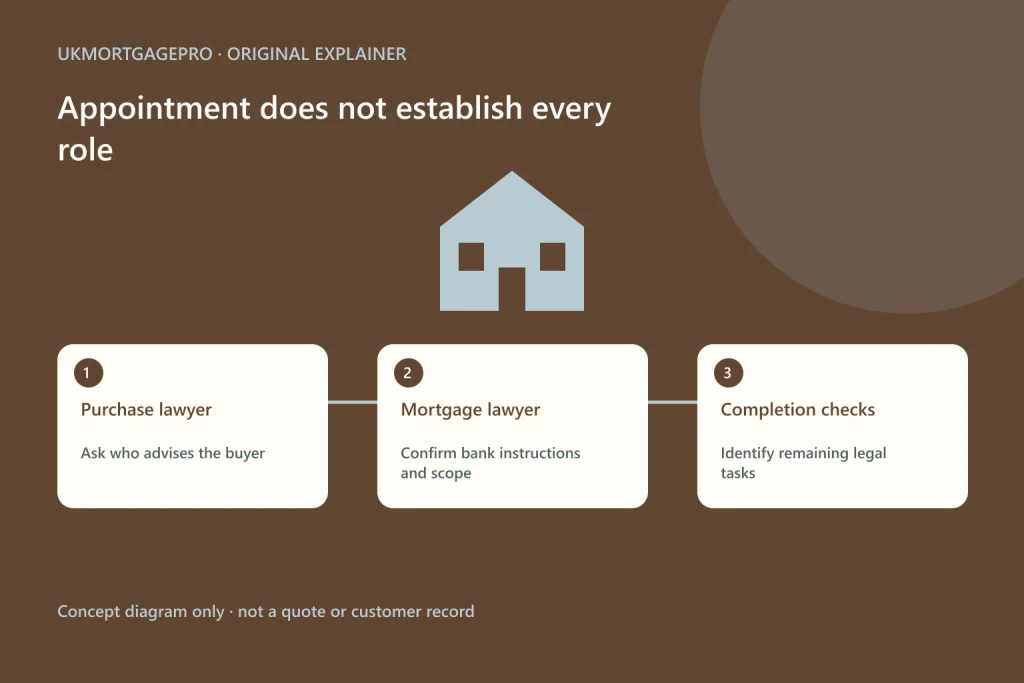
For a Singapore bank UK mortgage enquiry, a lawyer appointed for the property purchase and a lawyer appointed in connection with the mortgage may have different instructions. This guide examines representation and scope using DBS’s public overseas-property description. It does not repeat an off-plan financing timeline or recommend a particular law firm. Before relying on an appointment, ask who the professional acts for, what work is included and which UK purchase or mortgage tasks still need confirmation.
The first-party page has separate references
DBS Treasures Private Client’s overseas-property page refers to a purchase lawyer at the buying stage and a panel lawyer at loan acceptance. It also identifies customer-paid legal costs and further property and title work before completion. These references do not prove that two firms are always required or that one firm can always perform every role. They show why the actual appointment and scope must be clarified. The page is not an individual instruction or evidence of UKMortgagePro’s relationship with DBS.
An appointment is not completed advice
A name on correspondence can indicate who has been instructed, but it does not tell the buyer which checks have been performed or which concerns remain unresolved. Ask the lawyer to explain the actual stage and outstanding requirements within their role. Do not treat a welcome letter or receipt of documents as a certificate that the title, contract and bank conditions are all satisfied. This article does not decide whether legal work is sufficient or substitute for advice on a particular UK property.
Separate the client and the task
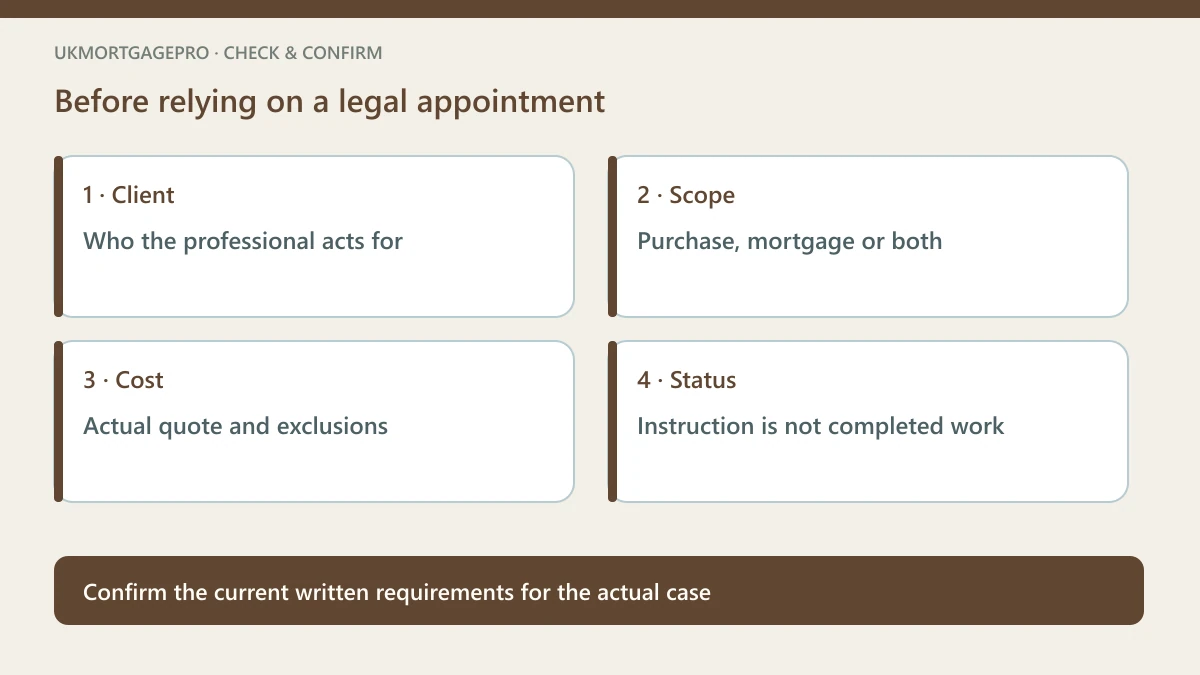
Ask whether the firm represents the buyer, the bank or another party, and whether the proposed work includes the purchase, mortgage security or both. Avoid assuming a bank-panel appointment provides personal advice on every contractual risk. If another professional is needed, the responsible lawyer should explain that requirement and any implications for communication. This guide does not determine conflict-of-interest rules or promise that a chosen firm is acceptable to the bank. No credentials or private instructions should be published in an enquiry.
Clarify the jurisdiction without guessing
The property may be in the UK while the financing discussion is with a Singapore bank. That alone does not establish which firm can undertake each legal step or which instructions apply. Ask the professionals and the bank to confirm responsibility for the actual property and facility. Do not infer authority from a firm’s address, a familiar name or involvement in a different transaction. UK title and bank-security tasks should not be marked complete because someone has merely handled an earlier overseas purchase.
Obtain a quote with a defined scope
Ask which legal work the quote covers, what remains excluded and when payment becomes due. DBS’s public page lists legal fees as a category; it does not supply a personalised all-inclusive legal price. If the transaction changes or extra work is identified, obtain a current explanation from the professional rather than using an old estimate. This guide publishes no fee amounts, deadlines or tax invoice. Any tax or other transaction liability needs separate qualified advice and current evidence.
Keep bank conditions and purchase advice separate
The bank can specify its financing conditions, while the buyer’s lawyer should explain the purchase contract and legal concerns within the appointment. A bank’s willingness to discuss finance is not an endorsement of the purchase. Conversely, a lawyer being satisfied with a legal issue is not lender approval of the borrower or property. Keep actual replies linked to the question answered; do not merge them into a single claim that the whole transaction is guaranteed to complete.
Use a responsibility register
A concise register can list task, professional, client represented, instruction date, evidence received and unresolved point. It should describe the actual replies, not create authority the professionals have not confirmed. For example, confirmation that a mortgage lawyer is appointed should be recorded as appointment, while completion of a property search remains a separate status. The register is an organisational suggestion, not a new legal procedure or a DBS-required form. Private correspondence should only travel through legitimate confirmed channels.
A focused initial enquiry
Initially describe the UK property location, purchase stage, intended bank route and whether any lawyer is already instructed, without uploading a contract or full financing document. UKMortgagePro can help organise questions but does not act as a conveyancer, verify title or guarantee DBS approval. Sources were checked on 6 October 2026; scope, costs and requirements can change and must be reconfirmed for the case. Financing does not remove purchase, valuation, currency or continuing-repayment risks.
Practical checklist
- Purchase and mortgage roles are explicitly confirmed.
- The client represented and legal scope are known.
- Quotes and exclusions relate to the actual transaction.
- Appointment and completed work have separate statuses.
Questions to clarify
Does the DBS panel reference prove one firm covers everything?
No. Ask the bank and appointed professionals to confirm the actual scope.
Are quoted legal fees a guarantee of completion?
No. Fees and appointment do not establish that all legal and lending conditions are met.
Sources and scope
- DBS Treasures Private Client — Overseas Property Financing — checked 2026-10-06; page publication/update date not stated or not established
Public information and document-organisation guidance only; not personal mortgage, legal, tax, valuation or investment advice, and not lender approval or endorsement. Confirm current case requirements with the responsible professionals.
Related information and consultation
Singapore-bank UK-property financing information · Mortgage information · News and practical guides · Arrange a consultation。Enquiry acknowledgement is not mortgage approval.