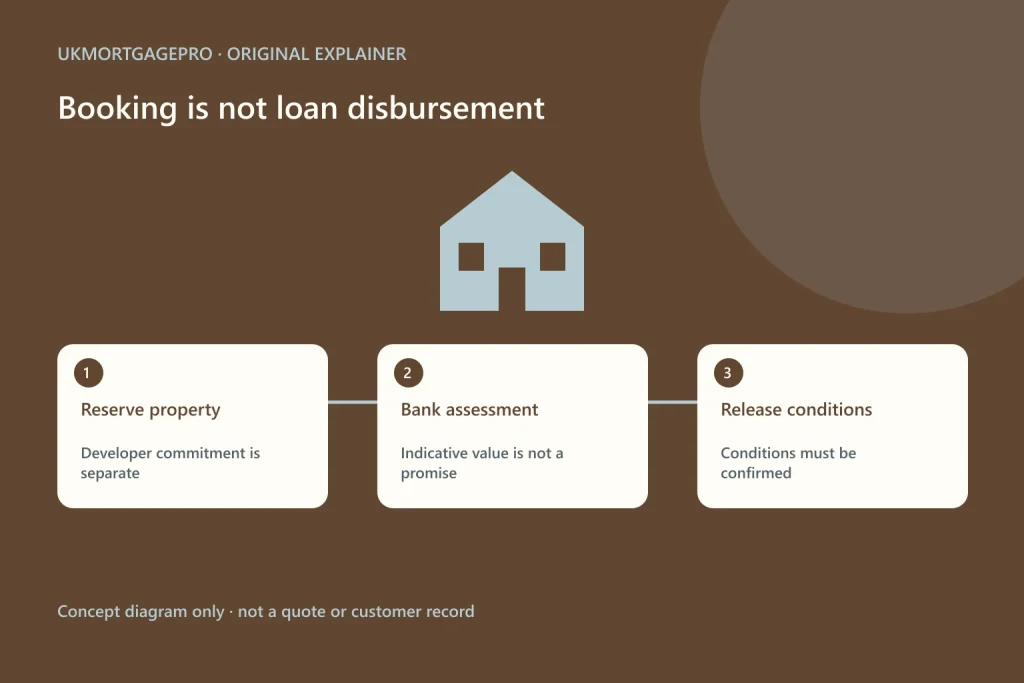
Focus on the financing gap
A Singapore bank UK mortgage for a London property under construction involves more than a developer reservation and a bank conversation. There can be a gap between committing to buy, receiving an indicative financing discussion and satisfying the conditions for disbursement. This article focuses on those distinct milestones. It does not repeat a London postcode eligibility guide, recommend buying off-plan, or promise that finance will be available when a development finishes. The buyer’s own conveyancer should explain the contractual exposure.
What the first-party page actually says
DBS Treasures Private Client’s overseas-property page describes financing for completed properties and properties under construction in London Zones 1 and 2. Its purchasing section separates committing to a purchase, seeking finance, loan acceptance, completion preparation and loan disbursement. The existence of those stages does not establish the borrower’s eligibility or approval. The page also warns that fees and deposit amounts can change. This article deliberately does not reproduce its example reservation or exchange deadlines as universal legal requirements.
Booking money has a different purpose
A reservation or developer deposit belongs to the property purchase arrangements. It is not evidence that a mortgage is approved or that the bank has accepted a particular valuation. Before making an irrevocable payment, ask your conveyancer about refundability, contract conditions and the consequences if finance is unavailable. Do not assume the developer can change the lender’s conditions, or that a financing enquiry shifts the contractual risk to the bank. A marketing timeline is not a guarantee of completion.
Indicative value is an assessment input
DBS’s page describes financing quantum by reference to the lower of purchase price and indicative valuation at its financing stage. That is not a commitment to fund a particular percentage in every case, nor a guarantee that a later valuation remains unchanged. Keep the agreed purchase price, the dated indicative figure and any later required valuation separately recorded. If a valuation changes, the cash difference may change as well. The bank must confirm the current financing amount and remaining conditions.
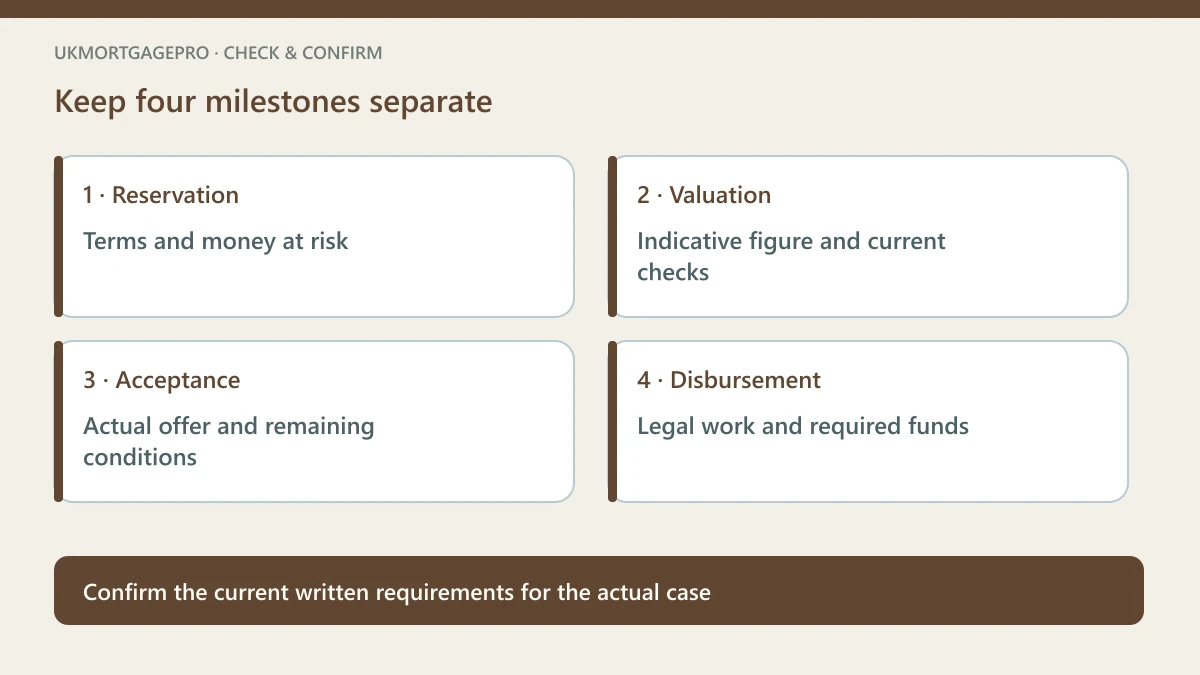
Acceptance still leaves conditions to check
An accepted loan offer is not the same event as the loan being paid out. Read the actual offer and ask which documents, legal steps, property conditions or payment arrangements remain outstanding. The DBS page mentions an appointed panel lawyer and customer-paid processing, legal and valuation fees at the acceptance stage. Those are categories to investigate, not a personalised fee quote. Ask the bank to identify the conditions that apply to the actual facility and how completion readiness will be confirmed.
Construction dates can move
If the completion forecast changes, tell the lender and the conveyancer rather than assuming the earlier schedule is still valid. Ask whether the offer, assessment or supporting evidence needs updating and whether a later disbursement date is possible. This article does not state a DBS offer-validity period that was not established from the source. A development completing later than expected can affect arrangements and cash timing, but the specific consequences should be answered from the contract and current bank correspondence.
Check the cash difference before release
The DBS page distinguishes the loan amount to be disbursed from the purchase price difference that must be available at completion. The sensible planning question is how much confirmed cash is needed, in which currency, at which date and through which authorised arrangement. Do not treat a future asset sale, predicted exchange rate or unconfirmed additional borrowing as cleared cash. If the loan is not denominated in sterling, confirm the bank’s currency and payment requirements without assuming conversion will happen automatically or without cost.
Keep tax and legal questions with the right people
A bank’s broad checklist of fees and taxes is not a statement that every named tax is immediately due on every purchase. The conveyancer and a qualified tax adviser must explain which charges or taxes apply to the actual transaction and when. This article therefore does not repeat the page’s broad tax list as a completion invoice. The same discipline applies to property insurance and title checks: their presence in a stage diagram is not proof that they have been completed for a buyer.
Use a milestone summary for consultation
An initial enquiry can describe the development location, construction status, intended completion month and whether there is already a reservation or offer, without uploading private contracts. The next conversation should identify outstanding bank and legal confirmations. UKMortgagePro does not represent DBS, claim a partnership or certify any development as financeable. Sources were checked on 3 October 2026; bank scope and case requirements should be reconfirmed before commitment. Financing an investment property does not remove the risks of valuation change, delayed completion or inability to keep up repayments.
Practical checklist
- Reservation terms are not described as mortgage approval.
- Purchase price and indicative valuation have separate dates.
- Actual offer conditions and current financing amount are confirmed.
- Completion cash, legal work and release instructions remain separate milestones.
Questions to clarify
Does “under construction” mean every off-plan property is accepted?
No. It describes a public product scope, not an approval of the particular property or borrower.
Can I use the bank’s example purchase timetable as my contract deadline?
No. Obtain the actual deadlines and risks from your conveyancer and the relevant agreements.
Sources and scope
- DBS Treasures Private Client — Overseas Property Financing — checked 2026-10-03; page publication/update date not stated or not established
Public information and document-organisation guidance only; not personal mortgage, legal, tax, valuation or investment advice, and not lender approval or endorsement. Confirm current case requirements with the responsible professionals.
Related information and consultation
Singapore-bank UK-property finance · Mortgage information · News and practical guides · Arrange a consultation。Enquiry acknowledgement is not mortgage approval.