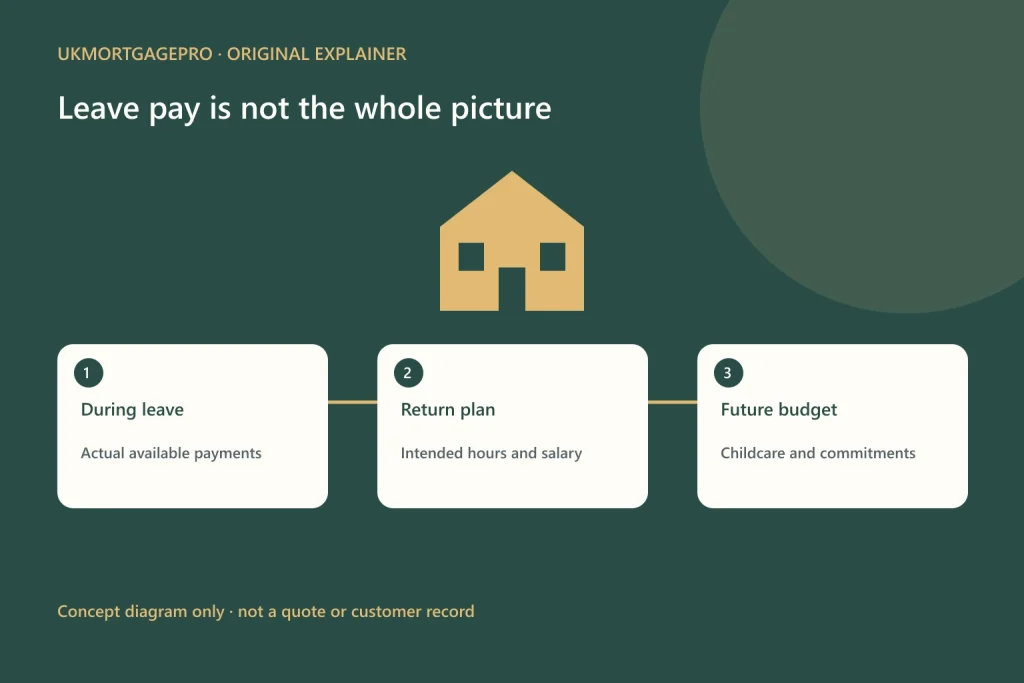
Three periods to describe
An overseas income UK mortgage enquiry during parental leave needs a clear description of the transition, not simply a copy of the highest historical salary. Separate income before leave, payments during leave and the intended return-to-work position. This guide concerns that change in circumstances; it does not repeat general payslip or currency-conversion guidance. It cannot establish eligibility for an overseas employee or tell an individual how much to borrow.
A narrow first-party example
HSBC UK publishes a parental-leave additional-information form for completion by a broker. It asks about work terms before and after leave, leave and return dates, expected childcare costs and how payments will be maintained during leave. This illustrates the information to clarify; it is not a form that this article tells readers to submit themselves. It is not a claim that UKMortgagePro has intermediary authorisation, represents HSBC or can apply the form to every overseas employment arrangement.
Record current leave payments honestly
Describe who makes the current payments, their currency and the period covered. Employer-funded pay, a public benefit and savings used for household spending are not interchangeable salary descriptions. Ask the responsible adviser what evidence is relevant to the actual product. Do not relabel transfers from savings as employer pay or copy an earlier full salary into a field asking about current receipts. An organisation receiving documents has not necessarily accepted that income.
Explain the intended return to work
The return plan should describe the intended date, working hours and pay terms, including anything that has not yet been confirmed. If a return on reduced hours is planned, say so rather than presenting the old full-time arrangement as certain. A statement of intention and an employer confirmation are different evidence. Ask the lender which documents it needs and who must issue them; do not create a purported employer letter or assume a personal summary meets its requirements.
Put childcare into the future budget
A return to work can involve expenses that were not present on older bank statements. List expected childcare arrangements and the basis of any estimate so the responsible professional can discuss the budget. Do not enter zero merely because a future invoice has not yet been issued. Where relatives may help, describe the actual plan and its uncertainty instead of treating informal support as a guaranteed permanent saving. This article supplies no affordability calculation.
Foreign leave systems need their own explanation
The UK policy example is not proof that a benefit with a similar English name in another country is equivalent. Explain the country, employer arrangement and actual source of payments, then ask whether the target lender can consider them. Translation may help a recipient understand a document, but it does not turn a foreign arrangement into a UK statutory benefit. Any eligibility, legal entitlement or tax treatment must be checked with the appropriate institution.
Keep the household bridge separate
If savings or a joint applicant help cover costs during leave, describe that bridge separately from the returning salary. Do not double-count the same money as both income and savings available for the deposit. The lender decides how it assesses the actual household circumstances; this guide does not prescribe a required reserve or permit using another person’s income without assessment. Initial enquiries should use a summary, not public copies of private bank or employment records.
An unresolved return plan stays unresolved
For example, a person may know the leave end date but not yet know whether their employer will agree to reduced hours. Record that uncertainty as a question for the employer and lender. Do not use an optimistic salary estimate to hide the unresolved work arrangement. This is a fictional organisation example, not a successful loan case or a recommendation to submit immediately. Any change after an application begins should be raised with the responsible people.
Create a short handover summary
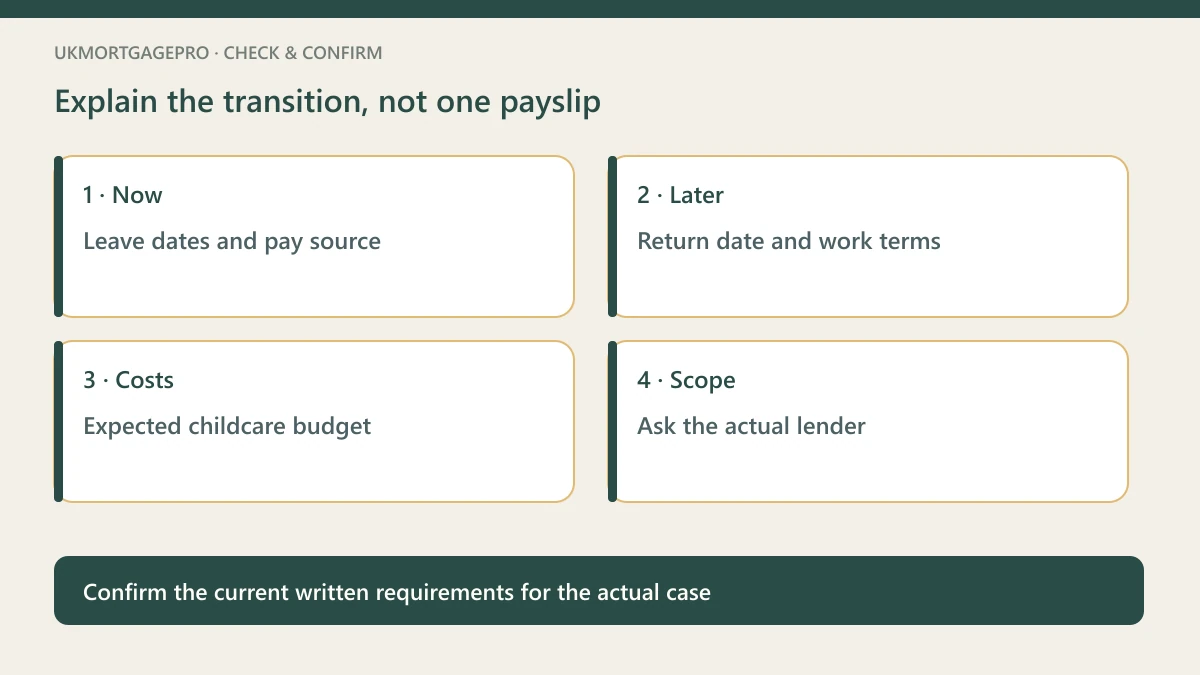
A useful personal note separates the actual leave period, current payment source, intended return terms, expected costs and outstanding confirmations. Label each fact by its source and date rather than combining everything into an unexplained annual number. Ask what needs updating when circumstances change. UKMortgagePro can help organise enquiry questions, but does not certify employment evidence or issue lender decisions. Sources were checked on 7 October 2026; confirm the current requirements for the actual case.
Practical checklist
- Separate earlier salary, current leave pay and intended return income.
- Describe reduced hours or an undecided return honestly.
- Include expected childcare and ongoing commitments.
- Confirm overseas applicability with the actual lender.
Questions to clarify
Does the published HSBC example guarantee acceptance of foreign parental-leave pay?
No. It is a specific broker-form example, not an overseas eligibility decision.
Can I describe my pre-leave salary as current leave income?
Not if that is not the actual payment. Explain each period and ask which evidence is required.
Sources and scope
- HSBC UK — Parental Leave Additional Information Form — checked 2026-10-07; page publication/update date not stated or not established
Public information and document-organisation guidance only; not personal mortgage, legal, tax, valuation or investment advice, and not lender approval or endorsement. Confirm current case requirements with the responsible professionals.
Related information and consultation
Overseas-income mortgage information · UK mortgage options · News and practical guides · Arrange a consultation。Enquiry acknowledgement is not mortgage approval.