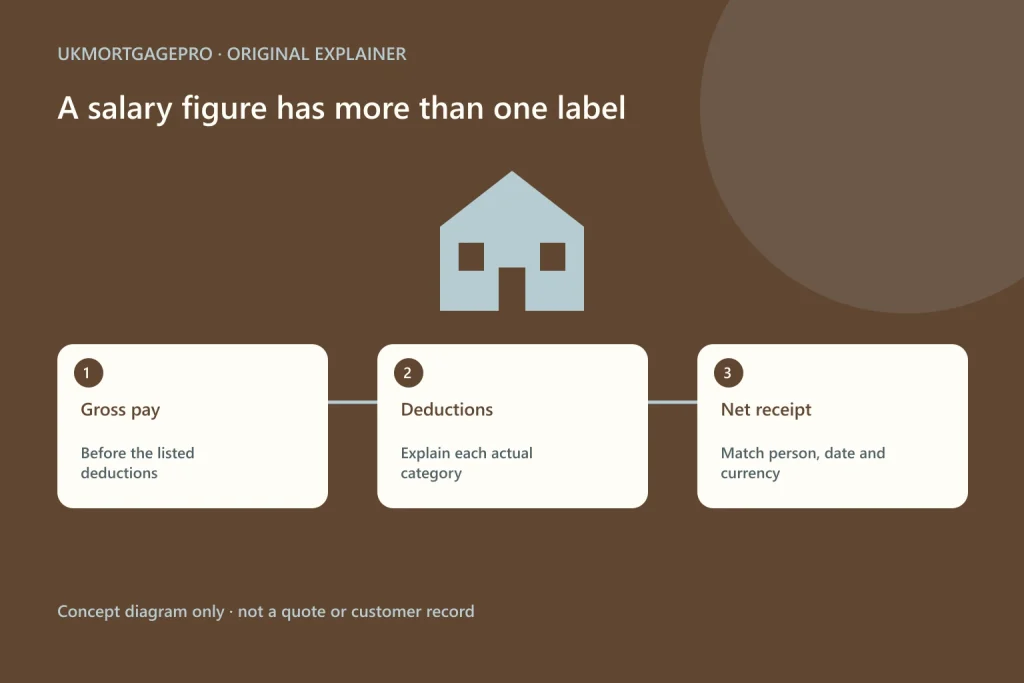
Start with the name of the figure
For an overseas income UK mortgage enquiry, gross pay, net pay and the amount credited to a bank account should not be presented as though they were identical. A payslip can show earnings before deductions while the statement shows money received afterward. The distinction does not determine the lender’s accepted income or the household’s affordability. This guide focuses on reconciling those labels, not assessing bonuses, converting a facility currency or constructing a joint-applicant total.
Preserve the original payroll categories
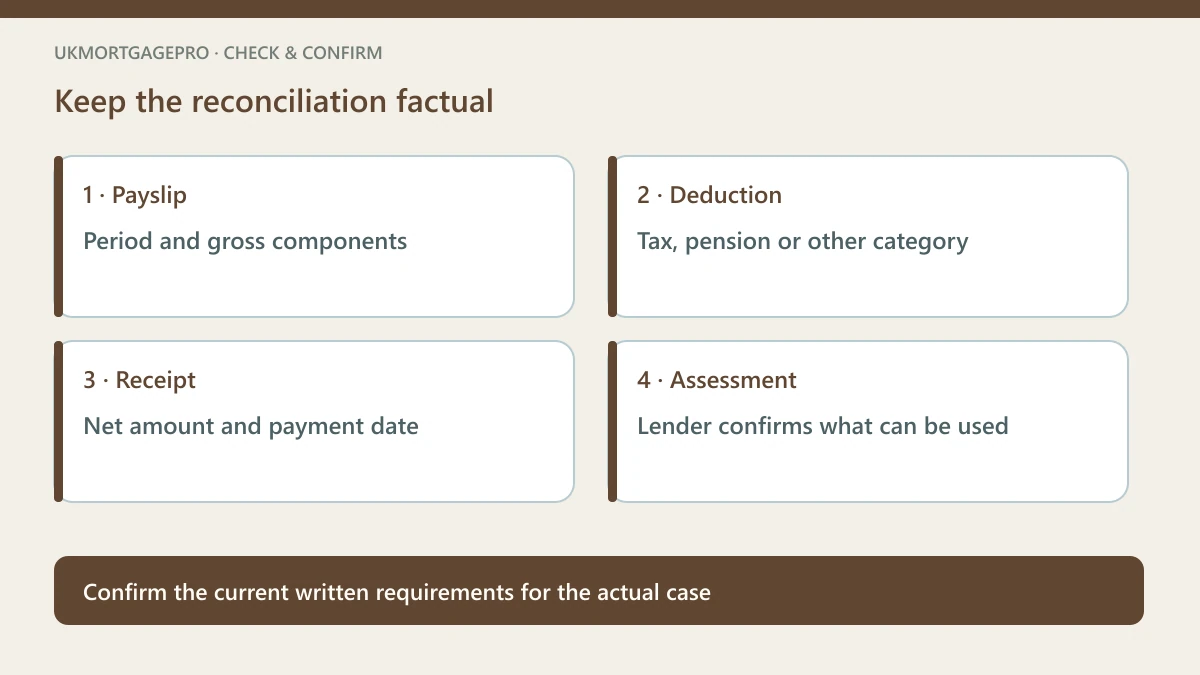
Record the payslip period, currency and the names of the gross and net fields. List the actual deduction categories rather than entering only a single unexplained difference. Tax, pension, voluntary deductions and repayments can have different meanings and should not all be relabelled as tax. If a label is unclear in the original language, ask the employer or appropriate payroll professional for an explanation. Do not alter the issued payslip or invent an English interpretation that changes the underlying figures.
Use lender instructions in their own scope
HSBC UK’s public intermediary packaging guidance requires income documentation to be consistent with the application. Its BTL foreign-currency instructions refer to gross income entered in sterling. That is a scoped example, not a universal rule for all residential or overseas borrowers. The target lender must confirm the income definition, acceptable categories and evidence required for the actual product. This guide does not use that example to announce an income multiple, a conversion discount or an individual borrowing limit.
Match one payment to its real period
A bank credit can arrive after the payroll period ends, and a payment date is not necessarily the final day covered by a payslip. Show both dates in the reconciliation. If payroll is split across two accounts, identify the two receipts as parts of the same payment rather than independent earnings. If several periods are settled together, do not label the full transfer as an ordinary monthly salary without explaining which periods it covers. The case handler determines what further evidence is appropriate.
Transfers do not create another salary
Moving money from a payroll account to another personal account produces a second transaction, not a second employment payment. Keep the employer-to-account trail separate from the later movement. Fees or currency conversion can also make the amount in another account differ from the payroll net figure. Explain the actual trail without adding both receipts as income. This is factual organisation, not advice to reroute funds or use a new account to make an application appear stronger.
Known deductions belong in the discussion
A recurring deduction can reflect a continuing commitment that matters to the wider application. Do not omit it just because a gross figure looks more favourable. Ask how the lender wants the deduction or associated obligation described and whether separate evidence is required. This article does not decide how a bank treats a pension contribution, employer loan or other item. It encourages an accurate explanation, with genuine uncertainty left unresolved rather than converted into a convenient assumption.
Do not annualise the wrong field
A year-to-date field, accumulated deduction or one-off adjustment should not be mistaken for one month’s recurring pay. Read the field label and the covered dates before multiplying any amount. An annualisation prepared for discussion should be clearly distinguished from a lender-confirmed assessment. If employment or pay arrangements have changed, state when the change occurred and which documents relate to each arrangement. A high bank balance is neither evidence of gross annual salary nor a guarantee of future payroll continuity.
A practical reconciliation without private details
For a first conversation, describe the employer country, pay frequency, gross/net distinction and reason for an unexplained difference. There is no need to publish account numbers or complete payslips. After the receiving professional confirms a suitable channel, provide the required original evidence and a separate explanatory summary. If the figures genuinely do not reconcile, ask payroll or the case handler to investigate; do not edit an original record to force an exact match.
The output is an explanation, not approval
A useful summary shows payroll period, gross pay, deduction categories, net pay and matched receipt, with any transfer or conversion kept separate. UKMortgagePro can help frame that enquiry but does not determine accepted income, change bank requirements or guarantee finance. Sources were checked on 6 October 2026. Reconfirm the actual product’s current rules and discuss repayments with the responsible adviser. Evidence clarity alone does not remove employment, currency, property or mortgage-repayment risk.
Practical checklist
- Every amount retains its original field name and period.
- Deductions are explained without concealing commitments.
- Transfers and split credits are not counted twice.
- The actual lender confirms the assessment basis.
Questions to clarify
Can I submit only the larger gross figure?
Follow the lender’s actual requirements and disclose the relevant facts; do not hide the net receipt or deductions.
Does a lower bank credit mean the payslip is wrong?
Not necessarily. Check deductions, timing, split payments and any later conversion before drawing a conclusion.
Sources and scope
- HSBC UK for Intermediaries — Packaging requirements — checked 2026-10-06; page publication/update date not stated or not established
Public information and document-organisation guidance only; not personal mortgage, legal, tax, valuation or investment advice, and not lender approval or endorsement. Confirm current case requirements with the responsible professionals.
Related information and consultation
Overseas-income and non-resident information · Mortgage enquiry information · News and practical guides · Arrange a consultation。Enquiry acknowledgement is not mortgage approval.