This article organises public information, not personal mortgage, legal or tax advice or lender approval. Requirements and product terms must be confirmed with the relevant lender or qualified adviser.
A salary amount is only the starting point
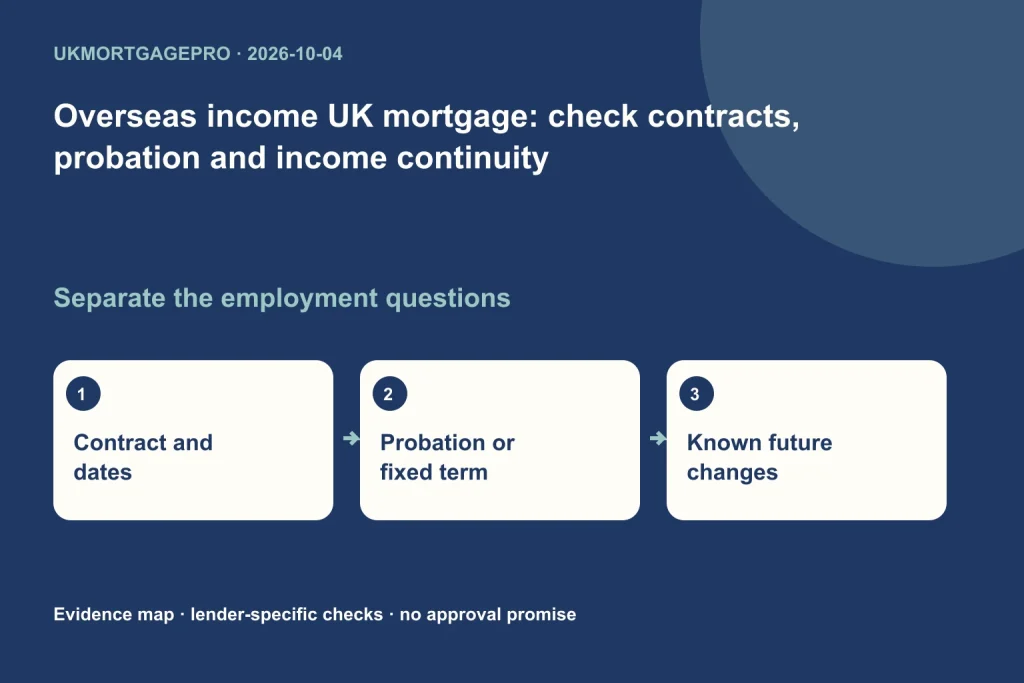
An overseas income UK mortgage enquiry should explain not only what you earn, but also the employment arrangement behind the salary. A permanent appointment, a probation period and a fixed-term assignment answer different questions. Start with a short factual employment timeline before discussing a borrowing figure. This article is an evidence-organising guide, not a list of lenders guaranteed to accept a contract, and it does not calculate how much overseas income a lender will recognise.
Put the actual contract dates in one place
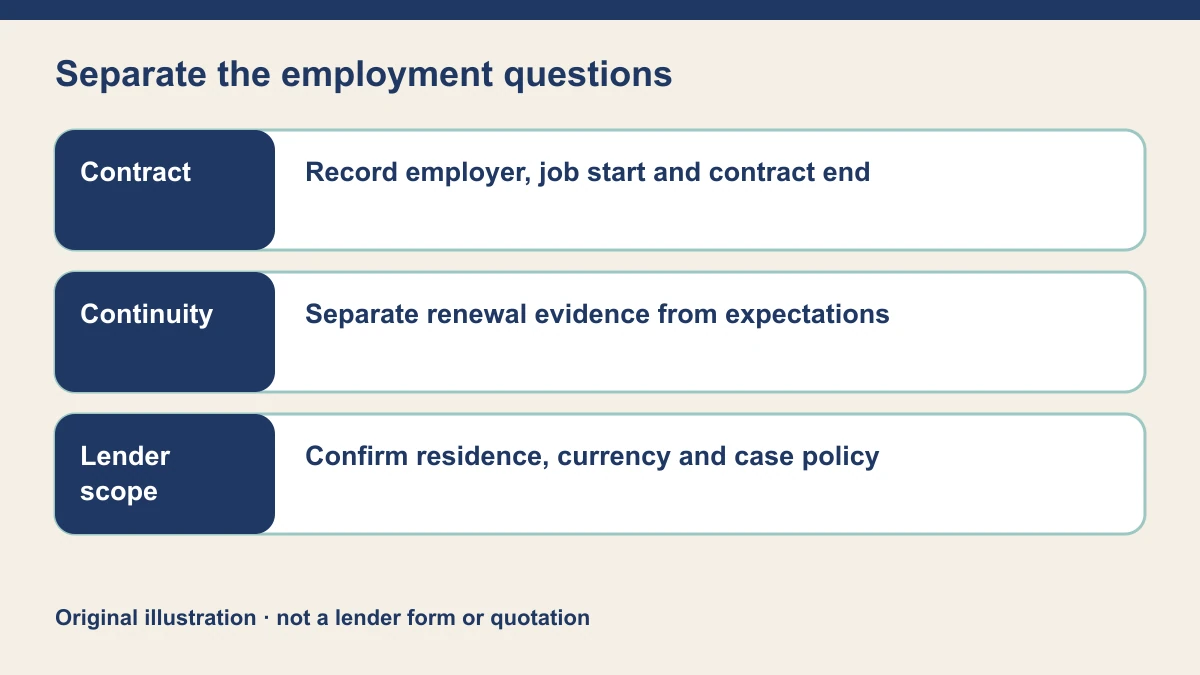
Prepare the employer’s legal name, your job start date, contract type, any stated end date and the currency in which you are paid. Add the date of the latest payslip and whether an amendment or renewal exists. As one first-party example, HSBC’s Application Help Centre says recent employment starts may prompt a contract request and asks for accurate employment status and employer details. That is a lender-specific public packaging example, not a rule that a contract alone proves affordability. (HSBC UK for Intermediaries — Application Help Centre)
Probation is not the same as temporary employment
Read the contract rather than treating every probation clause as a fixed end to the job. Identify whether the underlying appointment is permanent or temporary, and what the probation wording actually says. HSBC’s September 2026 useful-guide file describes a probation policy that depends on the employment contract and refers temporary arrangements to its fixed-term policy. This demonstrates why the contract classification matters; it is not confirmation that your overseas arrangement qualifies or that a later policy change cannot apply. (HSBC UK for Intermediaries — Useful Guide, September 2026 file)
For a fixed term, distinguish evidence from hope
Keep the signed contract, any signed extension and a factual work-history summary available if requested. An expectation that the employer will renew is different from a documented extension. Do not change an end date in a summary to make a contract look longer. HSBC separately publishes specific fixed-term policy changes for certain categories, including some professional and UAE-resident cases. Exceptions in a particular lender’s policy should be checked against the exact case and current criteria, not presented as a general overseas-contractor entitlement. (HSBC UK for Intermediaries — Fixed-term contract policy changes)
Tell the adviser about known changes
List any known change of role, employer, working hours or pay, with its expected date and supporting evidence where available. Keep current salary separate from an anticipated salary until the lender confirms the evidential route. HSBC’s application-help page asks about expected income and expenditure changes, including redundancy and role changes. The practical point is accurate disclosure, not a suggestion that every change prevents a mortgage. Do not omit a known reduction because an older payslip shows a higher amount. (HSBC UK for Intermediaries — Application Help Centre)
Employment acceptance and overseas eligibility are separate
A well-documented job does not settle whether a lender accepts your residence location, repayment currency or intended property use. HSBC’s international page has its own residence and product eligibility conditions and directs non-UK residents to an advised application route. Keep those checks separate from the employment checklist. Avoid applying a UK-resident employment example to every non-resident product, and ask the relevant lender or qualified adviser which policy applies to the actual arrangement. (HSBC UK — International property services)
A concise enquiry is more useful than a document dump
For an initial discussion, a redacted summary can state residence country, income currency, permanent or fixed-term status, contract dates and any imminent changes. Do not put an employment contract, passport or full bank statement into a public enquiry field. Once the case route and secure document channel are confirmed, provide the requested evidence without editing it. A factual summary helps identify questions early; it does not promise approval, a particular exchange-rate treatment, a rate or a completion date.
Sources and scope
- HSBC UK for Intermediaries — Application Help Centre
- HSBC UK for Intermediaries — Useful Guide, September 2026 file
- HSBC UK for Intermediaries — Fixed-term contract policy changes
- HSBC UK — International property services
Sources accessed on 3 October 2026. Access date is not a source publication date. Undated pages have publication/update date UNKNOWN; public lender examples are not individual eligibility confirmation.
This article organises public information, not personal mortgage, legal or tax advice or lender approval. Requirements and product terms must be confirmed with the relevant lender or qualified adviser.
Related information and consultation
Non-resident UK mortgages; UK mortgage information。 Consultation page — share a redacted summary first; enquiry acknowledgement is not mortgage approval.