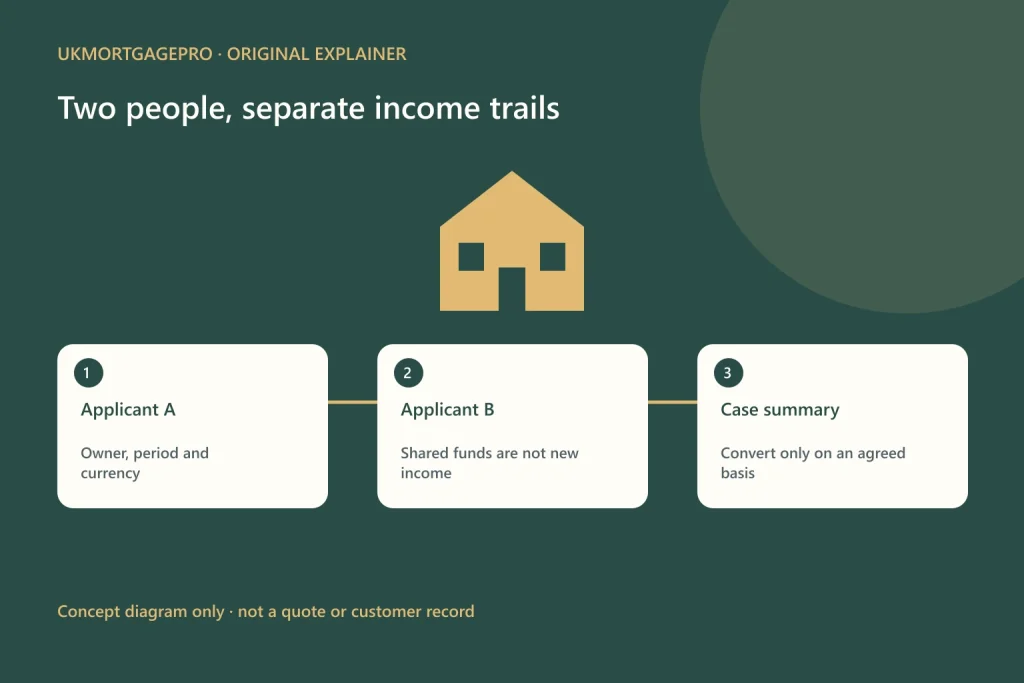
A joint total is the last step
An overseas income UK mortgage discussion can become confusing when two applicants earn in different currencies or receive money into shared accounts. Begin with a separate factual summary for each person, then ask the case handler how the incomes can be assessed together. This article addresses ownership and evidence organisation, not the general legal responsibility of joint borrowers and not employment probation rules. Adding two annual figures is not a lender decision about affordability or eligibility.
Create one row per actual source
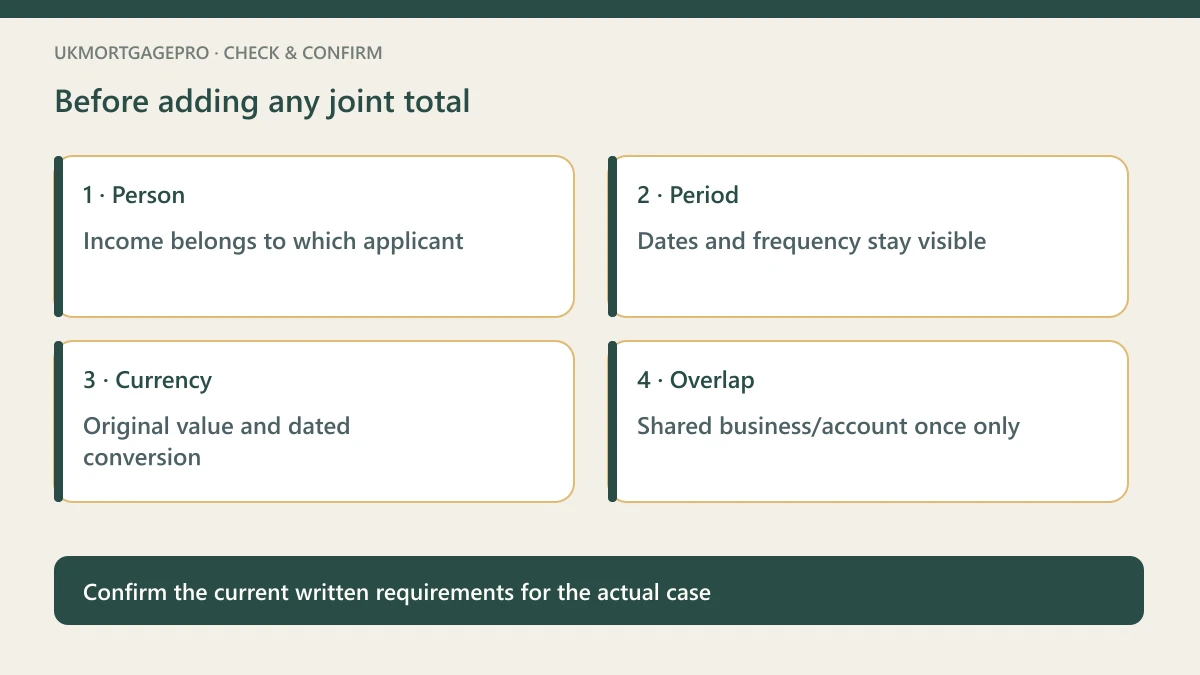
For each applicant, identify the employer, business, pension or other paying source, the original currency, payment frequency and evidence period. State who legally earns the money and which account receives it. A salary moving from a personal account to a joint account is still the same salary, not a second income source. A transfer from the other applicant should be described as a transfer, not relabelled as independent earnings simply because it appears in the recipient’s statement.
Shared businesses need a separate explanation
If both applicants have an interest in the same company or partnership, record each person’s role and ownership rather than attributing the whole business result to both. Company turnover, personal salary, profit share and distributions have different meanings. Ask the receiving lender which method applies and which evidence supports it. Do not combine the company’s retained profit with distributions of the same profit unless the case handler has confirmed an appropriate, non-duplicating calculation. The summary should preserve the original business periods.
Do not hide the original currencies
Keep the original amounts next to any sterling figure used for discussion. Record the date and purpose of a conversion, and label it as a working assumption until the lender’s method is known. HSBC’s intermediary packaging page includes foreign-currency income instructions in its BTL section; those instructions are not a universal residential policy and should not be copied to another product. A bank transfer’s exchange result also does not establish the lender’s income-assessment rate for either applicant.
Nationality, residence and income are distinct
Two joint applicants can have different residence or nationality positions even while buying the same property. HSBC’s public international-services page illustrates that its overseas channels have particular residence and income conditions. Evidence that one applicant meets a condition does not establish the position of the other, nor does a shared account establish eligibility. Identify each person’s current circumstances for the authorised adviser to check against the target product, rather than assuming one applicant’s status automatically covers the whole application.
Align dates before comparing figures
Applicants can be paid monthly, fortnightly, quarterly or through an annual business distribution. Show the actual periods instead of presenting the highest month for each and multiplying both by twelve. If one source has recently changed, tell the case handler which evidence relates to the old arrangement and which to the new. An outdated combined spreadsheet should not be used to conceal a known change. Materials from different years can be useful, but their dates must remain clear and their relevance confirmed.
Commitments also belong in the picture
A joint income summary is incomplete if it omits existing debts or continuing household commitments. Record who is responsible for each obligation and whether a shared payment appears in more than one document. A family agreement to split a payment does not necessarily change contractual responsibility. This article does not determine how a lender allocates joint debts; it encourages a clear factual explanation so the professional handling the case can apply the relevant assessment without relying on an arbitrary half-share.
Keep private evidence out of the enquiry
Before a channel is confirmed, an initial conversation can describe the two income categories, currencies, countries and purchase purpose without complete bank records or identification. Ask which evidence is actually needed for each applicant and how it should be sent. HSBC’s packaging page emphasises consistency between application details and supporting documents, but it does not authorise publicly uploading sensitive records. Do not edit an original statement to make names or dates fit; raise a genuine inconsistency with the case handler.
The useful output is an evidence register
A good register shows source, person, currency, period, receiving account category and unresolved question for every item. It avoids pretending that the register itself is an affordability calculation. UKMortgagePro can help organise that conversation but does not provide lender approval, promise a currency treatment or claim a banking partnership. Reconfirm current product requirements before the formal application. If repayments cannot be maintained, the mortgaged property can be at risk even when both applicants originally had substantial incomes.
Practical checklist
- Each source has one owner or a clearly evidenced share.
- Transfers between accounts are not counted as new earnings.
- Original currencies and periods remain visible.
- Product eligibility and the lender’s conversion method are still separately confirmed.
Questions to clarify
Can a joint account statement prove two incomes?
Only the actual sources and ownership establish the income trail. A shared account can receive one salary, two salaries or transfers with different meanings.
Can one applicant’s sterling income remove all currency questions?
No. Ask how the target lender treats each source and applicant; do not infer a universal joint-application rule.
Sources and scope
- HSBC UK for Intermediaries — Packaging requirements — checked 2026-10-03; page publication/update date not stated or not established
- HSBC UK — International Mortgage Services — checked 2026-10-03; page publication/update date not stated or not established
Public information and document-organisation guidance only; not personal mortgage, legal, tax, valuation or investment advice, and not lender approval or endorsement. Confirm current case requirements with the responsible professionals.
Related information and consultation
Overseas income and non-resident applications · Mortgage information · News and practical guides · Arrange a consultation。Enquiry acknowledgement is not mortgage approval.