Begin with the right cash question
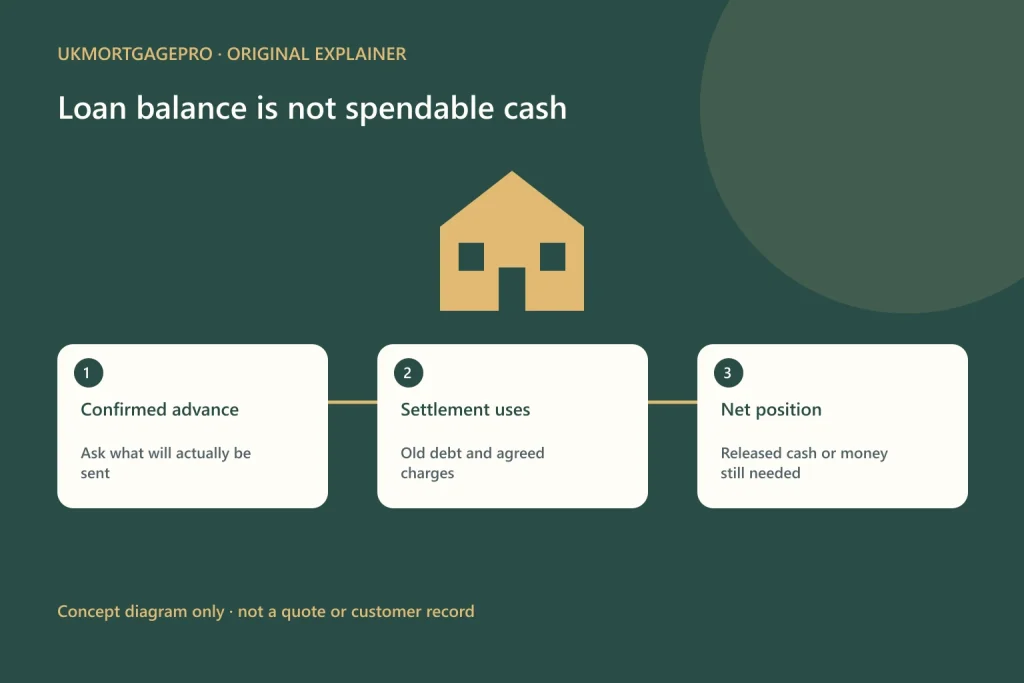
UK remortgage costs matter not only to the interest comparison but also to the amount of money available when the transaction completes. The mortgage balance shown in an offer is not automatically cash that a borrower can spend. This guide focuses on reconciling completion funds, not on the first monthly payment or a general product-fee comparison. Ask the case handler and conveyancer to distinguish the borrowing balance, the actual advance and the uses of that advance for the intended transaction.
Identify the actual advance
Confirm what amount the lender will release under the current accepted arrangements and whether the document being discussed is still indicative or final. Fees or other items can be treated in different ways, so do not assume the balance printed on one page equals the amount sent to the conveyancer. This article does not state a market-wide deduction rule or personalised net advance. The responsible professionals must explain how the actual offer and completion statement fit together.
Old borrowing has its own settlement figure
A lender switch usually involves settling the existing mortgage, but the exact redemption figure depends on the actual statement and relevant completion arrangements. Use the figure confirmed for the transaction, not a remembered online balance from an earlier date. This guide does not repeat a redemption-statement tutorial or invent an early-repayment charge. It explains why an old balance and a new advance cannot simply be subtracted without checking whether their dates and meanings correspond.
Keep confirmed charges separate
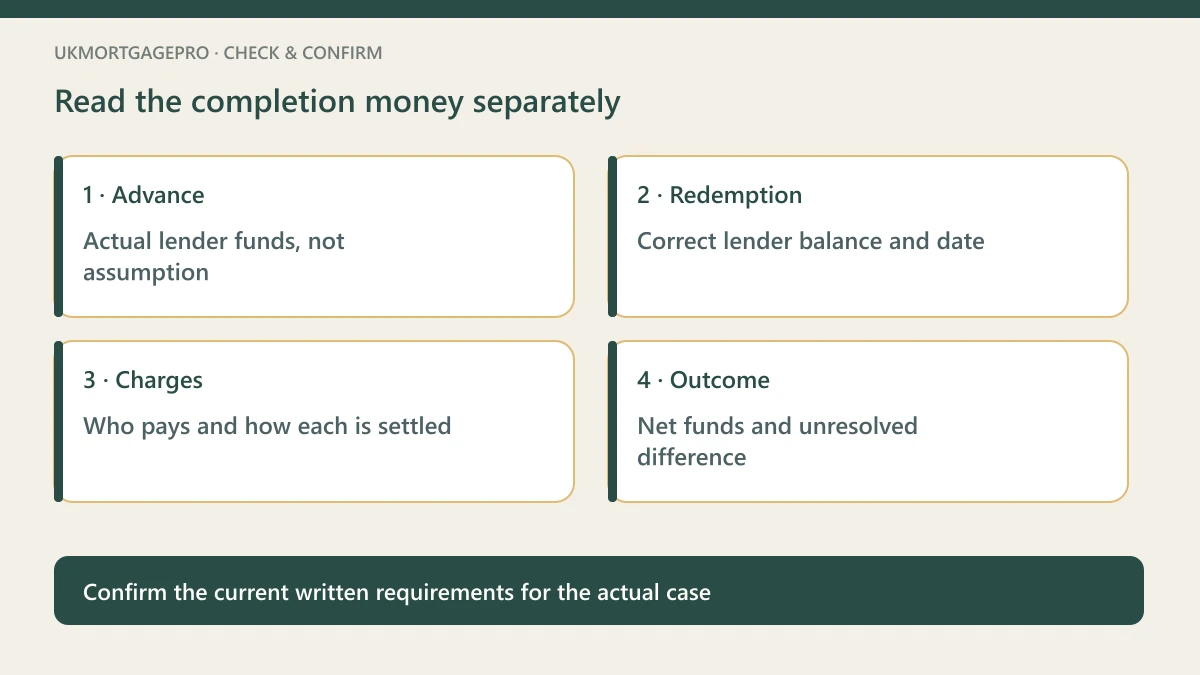
For each cost, record whether it is paid beforehand, settled from completion funds, added to borrowing or handled in another confirmed way. Do not count one fee both as an upfront payment and as a second deduction from proceeds unless the professionals explain that there are genuinely separate charges. MoneyHelper’s remortgaging guidance emphasises considering fees and overall costs; it does not certify the cash produced by an individual transaction. An apparent surplus on a personal spreadsheet is not a completion confirmation.
A lender’s legal process illustrates the distinction
HSBC UK’s public conveyancing information separates completion from later mortgage registration and describes legal work involved in repaying the old lender. That helps explain why funds have specific transaction uses rather than being wholly available for personal spending. This is a particular lender’s description, not a guarantee of timing, proceeds or eligibility for the reader. The current offer, conveyancer’s instructions and actual bank confirmation must govern the proposed transaction.
Do not spend a predicted surplus early
A planned release of equity remains conditional until the required decisions and legal arrangements are complete. Do not describe it to another party as cleared money merely because a mortgage application has progressed or an offer exists. If planned spending relies on those funds, explain the dependency and ask about timing. This article does not recommend additional secured borrowing for any purpose or promise that increasing a loan creates an equal amount of usable cash. Continuing repayments and borrowing costs remain relevant.
A shortfall is also a result
The reconciliation may show that additional money is needed rather than money being released. Keep that result visible, including which figure is confirmed and which remains uncertain. Do not fill the gap with predicted cashback, future income or an uncompleted asset sale while describing the budget as fully funded. Discuss the real funding position with the case handler and conveyancer. A source of money may itself require verification or approval; the fact that a spreadsheet balances does not complete those requirements.
Changing the date changes the question
If completion moves or the loan is amended, ask whether the redemption statement, advance arrangements or charge treatment need to be updated. Preserve previous versions as history rather than mixing an old deduction with a new advance. This guide does not establish a universal recalculation period or processing deadline. It encourages a clear record of the amount, date, purpose and source for each line so that the actual professionals can reconcile the transaction without relying on mismatched assumptions.
The practical handover
Use four headings: confirmed advance, confirmed settlement uses, other money required and the resulting net position. Leave unresolved figures visibly provisional. Initially describe the purpose and uncertain categories without uploading a complete statement or private bank details to a public form. UKMortgagePro provides information and an enquiry route, not a personal funding calculation, lender approval or conveyancing certification. Sources were checked on 6 October 2026. Confirm the actual arrangement before making commitments and consider the continuing repayment risk.
Practical checklist
- Balance, advance and net proceeds have distinct labels.
- Settlement figures use the relevant transaction date.
- Each charge appears once with its confirmed treatment.
- Provisional cash is not described as already available.
Questions to clarify
Does a larger offer mean the same increase in cash released?
Not necessarily. Reconcile the actual advance, settlement and charges.
Can predicted cashback be used as confirmed completion money?
Do not assume it is available then; check its actual conditions and timing.
Sources and scope
- HSBC UK — Conveyancing for existing customers — checked 2026-10-06; page publication/update date not stated or not established
- MoneyHelper — Remortgaging to get the best deal — checked 2026-10-06; page publication/update date not stated or not established
Public information and document-organisation guidance only; not personal mortgage, legal, tax, valuation or investment advice, and not lender approval or endorsement. Confirm current case requirements with the responsible professionals.
Related information and consultation
Remortgage options · Mortgage information · News and practical guides · Arrange a consultation。Enquiry acknowledgement is not mortgage approval.