This article organises public information, not personal mortgage, legal or tax advice or lender approval. Requirements and product terms must be confirmed with the relevant lender or qualified adviser.
Plan for the unfinished case as well as completion
When comparing UK remortgage costs, ask what you could still pay if the application is withdrawn, declined or does not reach completion. A completion-cost estimate and an unfinished-case estimate are different budgets. Start with a list of named charges and their written terms rather than a single headline figure. This article does not advise cancelling a mortgage application and does not promise that any lender, adviser or conveyancer will refund a particular charge.
Separate the person charging each fee
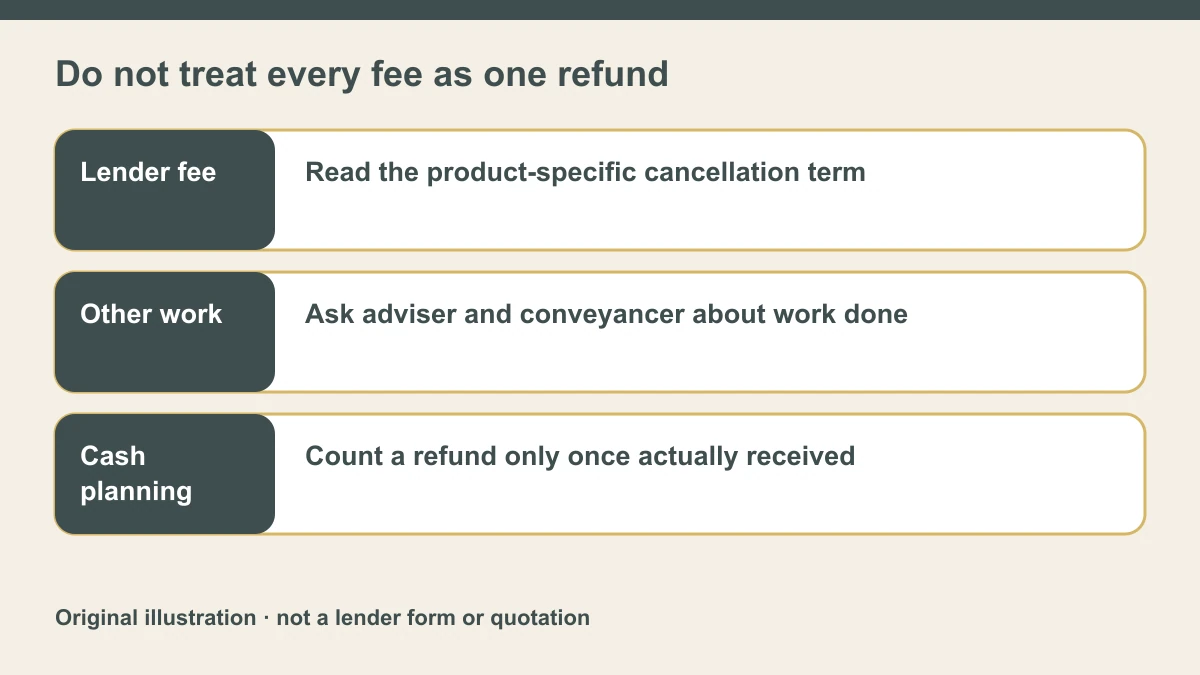
Create a fee register with the recipient, description, amount quoted, payment date, payment trigger and refund rule. Keep lender product fees apart from valuation work, adviser fees, legal work and any old-loan charges. A refund promise about one item does not settle the others. TSB’s published tariff distinguishes a lender product fee from legal costs charged by the solicitor. Use the quotation and engagement terms for your own case to establish which organisation answers each refund question. (TSB — Tariff of Mortgage Charges)
Read the actual product-fee wording
TSB’s public tariff says its product fee is refunded where the application fails or the customer withdraws it. Yorkshire Building Society’s fees page says it refunds its product fee where the mortgage does not complete. These are first-party examples of particular providers’ wording, not an industry-wide rule. Before paying, confirm that the term covers the exact product and transaction, how a refund is requested, who receives it and whether any conditions appear in your illustration or application documents. (TSB — Tariff of Mortgage Charges; Yorkshire Building Society — Mortgage affordability, fees and charges)
Ask about work that has already been performed
For every other charge, ask the organisation issuing the quote what happens before work starts, after work starts and after relevant third-party costs have been incurred. Does a quoted legal fee include disbursements, and is any element payable if completion never happens? Does a separately commissioned report have its own cancellation terms? These are questions to obtain a written answer, not assertions that all such charges are non-refundable. Do not borrow one lender’s product-fee policy to answer them.
Record why the case stopped, without guessing
A declined application, voluntary withdrawal, product change and expiry of an offer are not necessarily the same event under a fee agreement. Keep the actual event date and the correspondence identifying the charge. If the wording is unclear, ask the fee recipient to explain the applicable clause. Do not label a completed product switch as an uncompleted external remortgage. Ask the existing lender and adviser to confirm the actual stage before making a decision that could affect the current mortgage.
Do not spend a refund before it arrives
For cash planning, separate an expected refund from money already received. Record the original payment and the confirmed refund independently so a revised cost comparison does not deduct the same refund twice. If another application is being considered, ask whether it creates a new fee and what evidence of the first refund is needed. Avoid assuming the earlier payment automatically carries over or that someone else’s refundable charge removes the cash needed for a second process.
Keep the question set specific at consultation
A useful initial enquiry states the existing mortgage end date, proposed transaction, which fees have been quoted or paid and whether work has begun. Share no complete account numbers or sensitive loan documents in a public message. Ask the adviser to explain all relevant fees and conditional charges; MoneyHelper identifies this as part of understanding total mortgage costs. Keep the written answers with the comparison. A lower quoted rate or a refundable product fee alone does not prove the proposed remortgage is suitable or cheaper overall. (MoneyHelper — How to apply for a mortgage)
Sources and scope
- TSB — Tariff of Mortgage Charges
- Yorkshire Building Society — Mortgage affordability, fees and charges
- MoneyHelper — How to apply for a mortgage
Sources accessed on 3 October 2026. Access date is not a source publication date. Undated pages have publication/update date UNKNOWN; public lender examples are not individual eligibility confirmation.
This article organises public information, not personal mortgage, legal or tax advice or lender approval. Requirements and product terms must be confirmed with the relevant lender or qualified adviser.
Related information and consultation
UK remortgage information; UK mortgage information。 Consultation page — share a redacted summary first; enquiry acknowledgement is not mortgage approval.