A non-resident landlord may receive UK rent, pay a UK mortgage and hold cash reserves in another country. Those movements should not be collapsed into a single “rent covers the payment” assumption. The Non-resident Landlords Scheme affects how rent may be paid and tax deducted, while a mortgage provider conducts a separate affordability and property assessment.
HMRC states that NRLS applies to UK rental income where the landlord’s usual place of abode is outside the UK. It is not simply a nationality test and it may not match a person’s residence position for every other tax purpose. The scheme can apply to individuals, companies, trustees and partnerships, with additional rules for joint owners.
Where a letting agent operates the scheme, the agent generally deducts tax from the UK rental income and pays it to HMRC. In some situations a tenant may have responsibilities instead. HMRC can approve a landlord to receive rent without tax deducted, but the approval must be given in writing; it does not erase the landlord’s obligation to report and settle the correct tax through the relevant process.
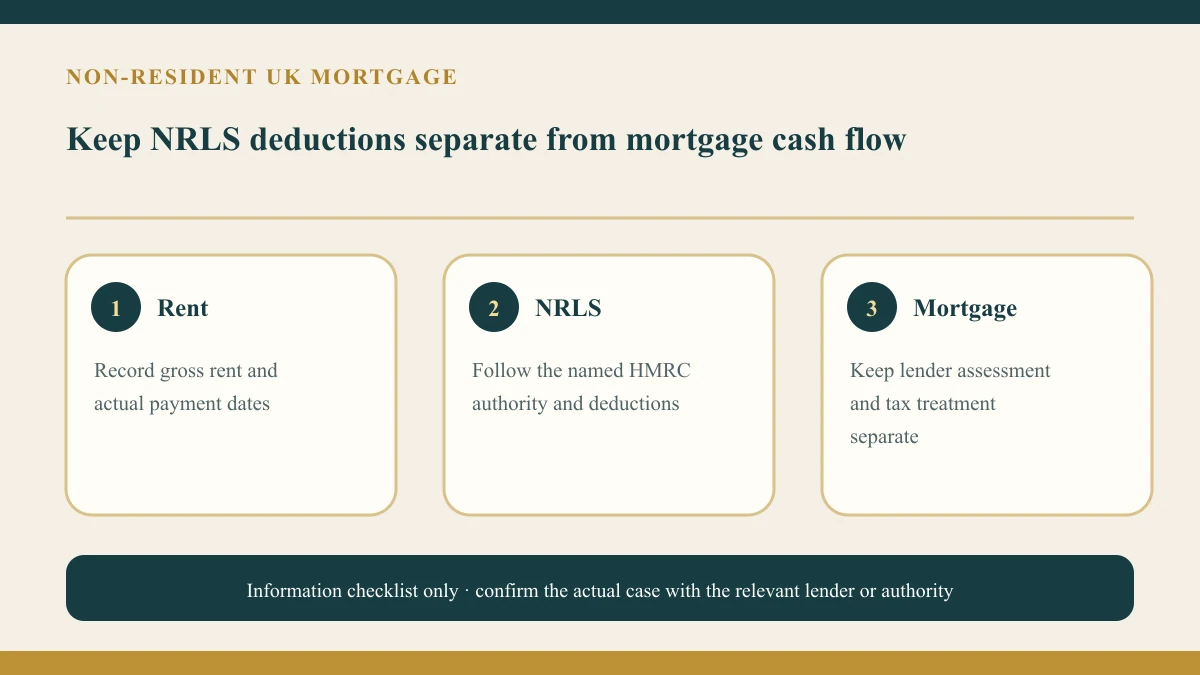
For mortgage cash-flow planning, record the gross rent, agent deductions, management and property expenses, tax withheld, money actually received and the mortgage payment as separate lines. The timing matters as well as the annual total. HMRC’s guidance uses quarterly accounting periods for agents and tenants who must operate the scheme, while the mortgage may be collected monthly.
An approval to receive rent without deduction should not be treated as a lender approval, a tax exemption or a guarantee that rent will meet mortgage payments. Likewise, a mortgage offer does not confirm how NRLS should be applied. The two decisions come from different organisations and use different evidence.
Joint ownership also needs a clear allocation. HMRC’s guidance explains that spouses or civil partners who jointly own property can each be treated separately for their share, and each person who wants to receive rent without deduction needs the relevant authority. A letting agent should follow the name and scope shown on HMRC’s notice rather than assume one owner’s approval covers everyone.
Before relying on projected rental income, keep a buffer for void periods, repairs, insurance, service charges and exchange-rate movements where funds are transferred overseas. Then confirm the provider’s current approach to rental assessment and the tax adviser’s view of the owner’s actual position. This produces a more realistic non-resident UK mortgage plan than comparing headline rent with the monthly payment alone.
资料来源与适用边界
- HMRC Non-resident Landlords Scheme guidance(2026-09-28复核)
This article organises public information and does not provide personal mortgage, legal or tax advice. Confirm the current position with the relevant lender, conveyancer, HMRC guidance or a qualified adviser.
继续了解与咨询
Related pages: non-resident UK mortgages、buy-to-let mortgages. Use the consultation page to organise questions; acknowledgement of an enquiry is not mortgage approval.